Receiving money from loved ones is a familiar part of Diwali celebrations, but not every cash gift receives the same treatment under income-tax laws. Whether the money is taxable depends on the relationship between the giver and the recipient, the total value of gifts received during the tax year and the mode of payment.
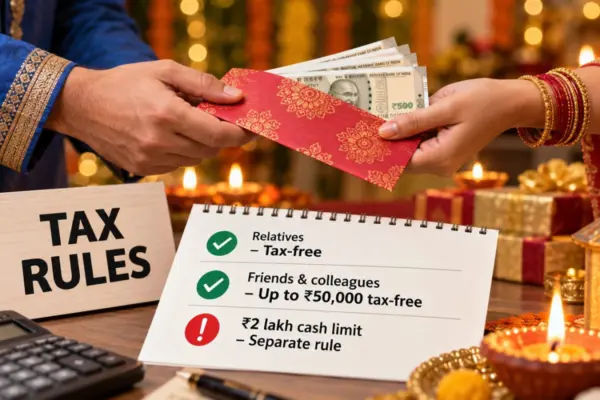
Under the Income-tax Act, 2025, gifts from specified relatives are generally exempt from tax, regardless of the amount. However, if gifts covered by the relevant provisions are received from friends, colleagues, neighbours or other non-relatives and their combined value exceeds Rs 50,000 during the tax year, the entire amount may become taxable.
Chartered Accountant Suresh Surana said recipients should distinguish between the exemption available for gifts from relatives and the threshold applicable to gifts from non-relatives. The relevant provision is Section 92(2)(m) of the 2025 Act, corresponding to Section 56(2)(x) of the Income-tax Act, 1961.
Rs 50,000 Threshold Applies to Combined Gifts
The ₹50,000 limit is calculated on the aggregate value of covered gifts received from non-relatives during the tax year. It is not a separate exemption for every individual gift.
For example, if a person receives Rs 25,000 from a friend, Rs 15,000 from a colleague and Rs 20,000 from a neighbour, the combined amount is Rs 60,000. As the total crosses the prescribed threshold, the entire Rs 60,000 may be taxable under the head ‘Income from Other Sources’, rather than just the additional Rs 10,000.
The amount is added to the recipient’s taxable income and taxed at the applicable slab rate. The final tax liability will depend on the individual’s overall income and the tax regime applicable to them.
Which Family Members Can Give Tax-Free Gifts?
The income-tax law provides an exemption for gifts received from specified relatives, irrespective of their value.
These include a spouse, siblings, siblings of the spouse or either parent, lineal ascendants and descendants of the individual or spouse, and the spouses of the specified relatives.
Accordingly, a cash gift from an eligible relative does not become taxable merely because it exceeds Rs 50,000. However, this income-tax exemption should not be confused with the separate rules governing large cash transactions.
Why Receiving Rs 2 Lakh in Cash Can Invite a Penalty
Apart from the gift-tax provisions, the law restricts certain cash receipts of Rs 2 lakh or more. Section 186 of the Income-tax Act, 2025, corresponding to Section 269ST of the 1961 Act, covers receipts in three circumstances:
- A total of Rs 2 lakh or more from one person in a single day.
- Rs 2 lakh or more in respect of a single transaction.
- Rs 2 lakh or more in respect of transactions relating to one event or occasion from one person.
These restrictions can apply even if the gift is exempt from income tax because the donor is a specified relative.
Surana said violations may attract a penalty equal to the amount received in breach of the provision under Section 451 of the 2025 Act, corresponding to Section 271DA of the 1961 Act. He recommended using bank transfers, cheques or other appropriate banking channels for high-value gifts instead of physical cash.
Gifts From Friends and Relatives: Key Difference
The tax treatment depends on both the source and the value of the gift. A gift from a specified relative is generally exempt, while gifts from non-relatives covered by the provision become taxable in full if their combined value exceeds Rs 50,000 during the tax year.
For instance, a person receiving Rs 75,000 in covered gifts from friends and colleagues may have to declare the entire amount as income from other sources. By contrast, a gift of the same value from a specified relative would generally qualify for the relative-based exemption. The separate restriction on large cash receipts must still be considered in both cases.
What Recipients Should Do
People exchanging cash gifts during Diwali should keep track of the total amount received from non-relatives throughout the tax year and establish the relationship with each donor. Maintaining records of the donor’s identity, the amount and the nature of the gift can help explain the transaction if questions arise.
For substantial gifts, recipients and donors should consider banking channels to avoid breaching restrictions on physical cash receipts. Understanding both sets of rules can help prevent an otherwise routine festive exchange from leading to an unexpected tax liability or penalty.