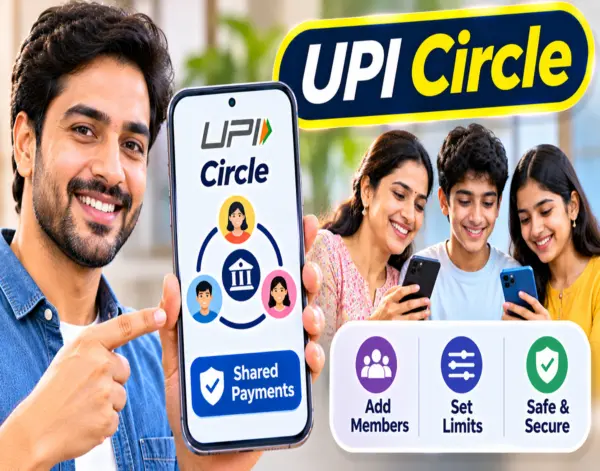
A family member can now make digital payments using another person’s bank account without having to know their UPI PIN, thanks to the UPI Circle facility. The feature allows an account holder to authorise trusted individuals to carry out transactions while retaining control over spending permissions and payment approvals.
Developed under the National Payments Corporation of India’s (NPCI) Unified Payments Interface (UPI) framework, UPI Circle introduces a delegated payment system in which one person provides another with access to make eligible transactions from their linked bank account. The facility is particularly useful for households where children, senior citizens or other family members need assistance with everyday digital payments.
Under this arrangement, the account holder is known as the primary user, while the person receiving payment access is called the secondary user. The primary user can decide whether the secondary user can make payments independently within an approved spending limit or must seek permission before every transaction.
What Is UPI Circle and How Does It Help Families?
UPI Circle is designed to make digital payments possible for individuals who may not have an independent UPI-linked bank account or need support from another person to manage transactions.
Instead of sharing banking credentials, the primary user creates an authorised payment arrangement through a UPI application that supports the feature. Once the secondary user accepts the invitation and completes the required setup, they can make eligible payments using the primary user’s account.
The facility does not transfer ownership of the bank account. The money continues to be debited from the primary user’s account, and transactions remain subject to the permissions and limits applicable to the arrangement.
Full Delegation and Partial Delegation: What Is the Difference?
UPI Circle provides two ways to authorise another person to make payments. The primary user can select the method according to the level of control they want to maintain.
| Feature | Full Delegation | Partial Delegation |
|---|---|---|
| How it works | Secondary user can complete eligible payments independently | Secondary user sends a payment request |
| Approval | No separate approval for every eligible payment | Primary user must approve each payment |
| Spending control | Predefined spending limit | Individual transaction approval |
| Suitable for | Regular household expenses | Payments requiring closer supervision |
Full Delegation: Under this option, the primary user allows the secondary user to make eligible payments without seeking approval for every transaction. A monthly spending limit is set in advance, making the facility useful for routine purchases such as groceries, transport and other household expenses.
Partial Delegation: In this arrangement, the secondary user can initiate a payment request, but the primary user must approve it before the transaction is completed. This option is suitable for parents or account holders who want to examine every payment before allowing money to be debited.
UPI Circle 2026: Transaction Limits and Spending Rules
The amount that can be spent through UPI Circle depends on the delegation method and the applicable rules. Under the full-delegation framework, the commonly specified maximum limit is ₹15,000 per month for each authorisation, with an individual transaction limit of ₹5,000.
The secondary user can make payments within the approved monthly allowance without obtaining separate permission for every eligible transaction. In partial delegation, payments require the primary user’s approval and are governed by the applicable UPI transaction limits.
Users should check the latest conditions displayed by their bank and UPI application, as additional restrictions and security requirements may apply.
Who Can Use UPI Circle?
The facility is intended for situations where a person needs payment access but another individual manages the linked bank account.
Parents and children: Parents can provide controlled payment access to eligible children for daily or educational expenses. They can choose a delegation method and set spending permissions according to their requirements.
Senior citizens: Elderly people who are uncomfortable using digital payment applications can receive assistance from trusted family members. The arrangement allows them to participate in digital payments without sharing the primary user’s banking credentials.
People without their own bank-linked UPI account: Eligible secondary users can make payments through the delegated arrangement even if they do not have a separate bank account linked to UPI.
Households managing regular expenses: Families can use the facility to distribute responsibility for routine purchases while keeping payments connected to the primary account holder’s bank account.
How to Set Up UPI Circle on a Payment App
Users can activate the feature through a participating UPI application. The general process involves these steps:
- Open a UPI application that supports UPI Circle.
- Find the UPI Circle or delegated payment section.
- Select the option to add a secondary user.
- Choose the person’s contact or enter their details using the available method.
- Verify the details before sending the invitation.
- Select full or partial delegation, depending on the options provided.
- Set the permitted spending limit and other applicable conditions.
- Complete the required authorisation.
- The secondary user must accept the invitation and finish the setup.
- Review the arrangement before allowing payments.
The exact steps may differ between applications. Some platforms may also require additional identity verification or security checks.
Can the Primary User Monitor or Stop Payments?
Yes. UPI Circle is designed to keep the primary user involved in managing delegated access. The available controls depend on the participating application.
In full delegation, the primary user can monitor transactions made within the authorised spending limit. In partial delegation, the account holder reviews and approves individual payment requests.
Participating applications may also allow the primary user to modify spending permissions or revoke a secondary user’s access. Users should check their application’s settings for the available options.
Is UPI Circle Safe to Use?
UPI Circle provides a formal way to delegate payment authority without disclosing the primary user’s UPI PIN or banking password. However, account holders must exercise caution because authorised transactions are debited from their own bank accounts.
Users should follow these precautions:
- Add only individuals they know and trust.
- Verify the secondary user’s details before approving an invitation.
- Set spending limits carefully.
- Understand the difference between full and partial delegation.
- Never share UPI PINs, passwords or OTPs.
- Check transaction alerts and bank statements regularly.
- Revoke access when it is no longer required.
- Report suspicious transactions to the bank immediately.
Users should activate the feature only through an authorised UPI application and avoid following instructions from unknown callers or suspicious links.
Where Can Users Get Help?
For information about UPI-related services, users can visit NPCI’s UPI Help platform at upihelp.npci.org.in. For account-specific issues, they can contact their bank or UPI application provider.
If a person suspects financial cyber fraud, the incident can be reported through the national cybercrime helpline 1930 or the official Cyber Crime Reporting Portal.
How UPI Circle Could Change Everyday Digital Payments
UPI Circle offers families an alternative to sharing cash or confidential banking details when another person needs to make routine payments. By introducing delegated access, it allows account holders to decide who can transact through their bank account and under what conditions.
The feature could be particularly helpful for parents managing children’s expenses, families assisting senior citizens and households where one person handles the main bank account. However, the primary user remains responsible for the funds used through the arrangement and should carefully monitor the payments being made.
UPI Circle therefore combines convenience with spending controls, making it possible to extend digital payment access to trusted individuals without handing over unrestricted access to a bank account.